M1 Finance vs Betterment (2026): Which Is Right for You?
M1 Finance gives you full control over your portfolio. Betterment automates everything. Here's exactly which one wins — and when.
KatchingStacks is reader-supported. When you open an account through links on this page, we may earn a commission at no extra cost to you. See our affiliate disclosure and editorial policy.
Betterment and M1 Finance are both popular investing platforms — but they’re built for completely different types of investors. Betterment manages everything for you. M1 gives you control over exactly what you own, then automates the execution.
If you’re trying to decide between the two, the choice usually comes down to one question: do you want to pick your investments, or do you want someone else to handle it?
Quick Comparison: M1 Finance vs Betterment
| Feature | M1 Finance | Betterment |
|---|---|---|
| Management fee | $3/mo (waived at $10K+) | 0.25%/yr or $5/mo (<$24K) |
| Minimum to invest | $100 ($500 for IRA) | $0 ($10 to start) |
| Portfolio control | Full (you build Pies) | Pre-built only |
| Tax-loss harvesting | No (tax minimization only) | Automated |
| Individual stocks | Yes | No |
| Margin borrowing | ~4.4% (at $2K+) | No |
| Human advisors | No | Premium plan |
| Cash account | Checking account | 4.75% APY savings |
| Crypto | Via partner | Yes |
Fees: M1 Finance Wins for Large Accounts
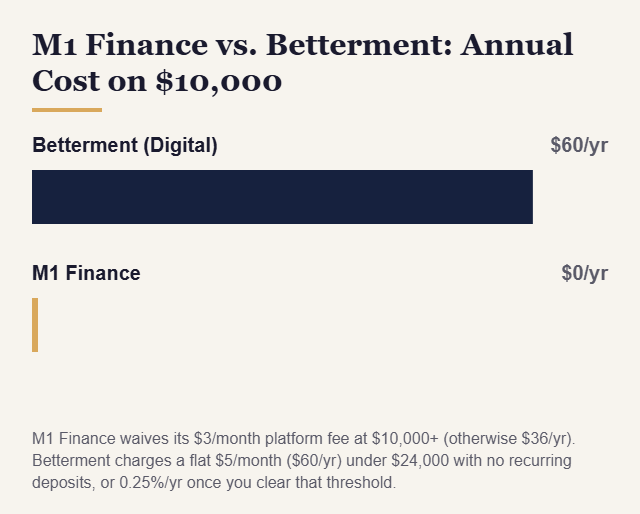
M1 Finance charges a $3/month platform fee — but it’s completely waived if you keep $10,000 or more across your M1 accounts. Below that threshold, you’re paying $36/year regardless of your balance.
Betterment charges 0.25%/year once your balance reaches $24,000 (or you set up $200+/month in recurring deposits) — otherwise it’s a flat $5/month. The flat fee works out cheaper only below $24,000 in the rare case you’d choose 0.25% voluntarily; in practice, smaller accounts without recurring deposits are stuck with the $5/month flat rate.
On a $50,000 portfolio: Betterment costs $125/year. M1 Finance costs $0 (fee waived). On a $5,000 portfolio: Betterment costs $60/year (flat fee, under $24,000) vs M1’s $36/year — M1 still wins.
Winner: M1 Finance — especially once you cross $10K.
Portfolio Control: M1 Finance Is in a Different Category
M1 Finance uses a “Pie” system — you build a portfolio by selecting any combination of stocks and ETFs and setting target percentage allocations. M1 then automatically buys and rebalances to maintain those targets. You can hold individual stocks like Apple or Nvidia alongside ETFs — all in the same portfolio.
Betterment offers pre-built portfolios only. You pick a risk level and Betterment picks the ETFs. You can’t add individual stocks, customize ETF weights, or build your own allocation from scratch.
Winner: M1 Finance — by a wide margin for anyone who wants control.
Tax Efficiency: Betterment Wins
Betterment offers automated tax-loss harvesting on all taxable accounts at no extra cost — continuously scanning for opportunities to sell losing positions and offset gains. Betterment claims nearly 70% of customers using it cover their advisory fee through estimated tax savings.
M1 Finance does not offer automated tax-loss harvesting. It has a “tax minimization” feature that sells highest-cost lots first when you reduce a position — better than nothing, but not the same as proactive harvesting.
Winner: Betterment
Margin Borrowing: M1 Finance Only
M1 Finance offers a portfolio line of credit at roughly 4.4% interest for accounts with $2,000+. You can borrow up to 40–50% of your portfolio value without selling positions — one of the best margin rates available for retail investors.
Betterment offers no margin borrowing at any tier. Taking a portfolio loan is often cheaper and more tax-efficient than selling investments and triggering capital gains — so this is a real practical advantage for M1.
Winner: M1 Finance
Automation: Betterment Wins
Betterment is fully automated. Set your goal and risk level, deposit money, and Betterment handles rebalancing, dividend reinvestment, tax-loss harvesting, and goal tracking. You never need to log in except to check your balance.
M1 automates execution once you build your Pie — but you decide what’s in it. It requires more upfront thinking and occasional attention. Not a lot, but more than Betterment.
Winner: Betterment for truly hands-off investors.
Human Advisors: Betterment Only
Betterment’s Premium plan (0.65%/yr, $100K minimum) includes unlimited calls and messaging with Certified Financial Planners. M1 Finance has no human advisor option at any price.
Winner: Betterment
Who Should Choose M1 Finance?
Choose M1 Finance if you want to hold individual stocks alongside ETFs, have $10K+ and want to pay zero management fees, want cheap margin borrowing as a liquidity tool, or have strong convictions about specific sectors or companies.
Who Should Choose Betterment?
Choose Betterment if you want a completely hands-off experience, have a large taxable account and want automated tax-loss harvesting, want access to a human financial planner, or are starting with less than $100 (Betterment has no minimum).
The Bottom Line
M1 Finance is the pick if you want control over what you own and don’t need someone else to manage it. The Pie system is genuinely powerful, fees are lower at scale, and margin rates are hard to beat.
Betterment wins if you want a set-it-and-forget-it experience with real tax efficiency built in — especially for large taxable accounts where tax-loss harvesting compounds into serious money.
Read our full Betterment review or see how Betterment stacks up in our Betterment vs Wealthfront comparison.
The 10-Year Fee Gap in Real Dollars
Percentages are easy to skim past. Here’s what the fee difference actually costs over a decade, assuming your balance holds roughly steady at each level (real accounts grow, but this isolates the fee gap on its own):
| Balance | M1 Finance (10 years) | Betterment (10 years) | Difference |
|---|---|---|---|
| $5,000 | $360 | $480 | M1 saves $120 |
| $10,000 | $0 (fee waived) | $480 | M1 saves $480 |
| $50,000 | $0 (fee waived) | $1,250 | M1 saves $1,250 |
The crossover is almost entirely about that $10,000 waiver threshold. Below it, M1’s flat $3/month is a fixed cost no matter what — a $1,000 account pays the same $36/year as a $9,000 account. Cross $10K and the fee disappears completely, which is why M1 pulls dramatically ahead for anyone with a mid-five-figure account or larger.
My Honest Take
I’d push most people toward Betterment first, even though M1 wins on pure fee math once you’re past $10K. Here’s why: the Pie system is genuinely fun to use, and “fun to use” is exactly the trap. Once you’re picking individual stocks alongside your ETFs, it’s very easy to start tinkering — chasing a hot pick, overweighting a stock you like, checking the account more than you should. Betterment’s lack of options is a feature disguised as a limitation. It removes the temptation entirely.
M1 makes sense once you’ve proven to yourself you can hold a portfolio without fiddling with it. If you’re not sure yet, that’s worth knowing before the zero fee becomes the deciding factor.
There’s also a real switching cost most comparisons skip. Moving from a percentage-fee robo-advisor into a self-directed Pie means giving up automated tax-loss harvesting, which for a taxable account with meaningful gains and losses to offset can be worth more than the fee you’re saving. Run the actual math on your own account before assuming zero fees automatically means more money in your pocket — for a large taxable account, Betterment’s 0.25% can pay for itself several times over in a single volatile year.